

Dearest reader, I come bearing news. Elon Musk, recently minted as the “world’s first trillionaire”, has managed to do something that to my eye looks quite risky long term; something built on a foundation of sand, assembled out of playing cards, and balanced on a fucking egg. Swept up in the headlines of the SpaceX IPO, I saw something people appeared to miss at first read, some cracks in the newly poured foundation: The simple truth of what SpaceX really is now, and what the real numbers break down into.
On with it.
The IPO
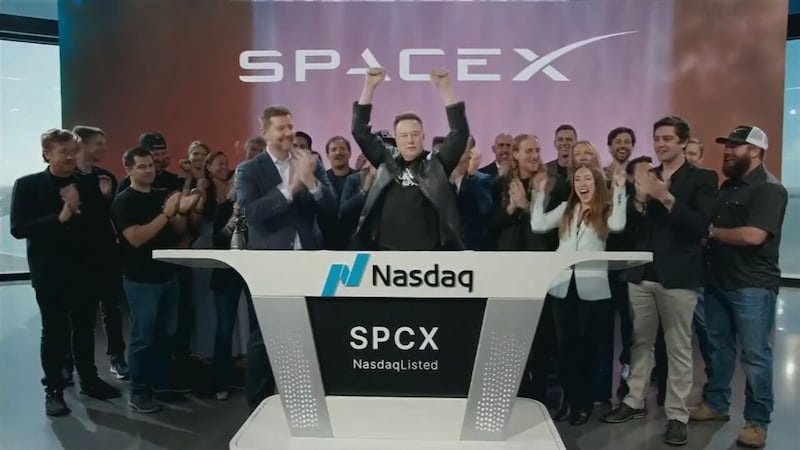
(Screengrab from the SpaceX side of the IPO, with Musk wearing his best formal t-shirt.)
As I’m sure you’re aware, Elon Musk owns SpaceX. This is not a contested fact. Elon also owns xAI, and this is not a contested fact. In March 2026, SpaceX moved to bring xAI into its orbit, acquiring it with limited fanfare. Fast forward to now, and SpaceX -the combined “1.25 trillion USD” company - was being listed on the NASDAQ.
The details of the deal interested me far more than anything about the headline figures. We’ll get to that in a moment – you need your context window refreshed. Headline figures:
xAI 2026 Q1 Capital Expenditures: $7.7 billion
SpaceX Spending v revenue as percentage: 2023 42%, 2026 Q1: 215%
SpaceX 2025 revenue: $18bn – net loss $5bn
The NASDAQ IPO has the combined SpaceX/xAI entity at $26.5 TAM (total addressable market), of which 80%+ is related directly to xAI; the current combined entity being classified under code 7370 - “Computer programming / data processing services etc”. Not an aerospace or telecommunications, but data centers and compute. AI. Grok.
Sounds good, right? What’s not to love about a bunch of eggheads making rockets and AI robots? It’s a marriage made in Heaven, surely. Rockets, AI, and robotics. Asimov smiles. Foundations of future space exploration unfolding before our eyes.
Therein lies the rub.
Grok Monster
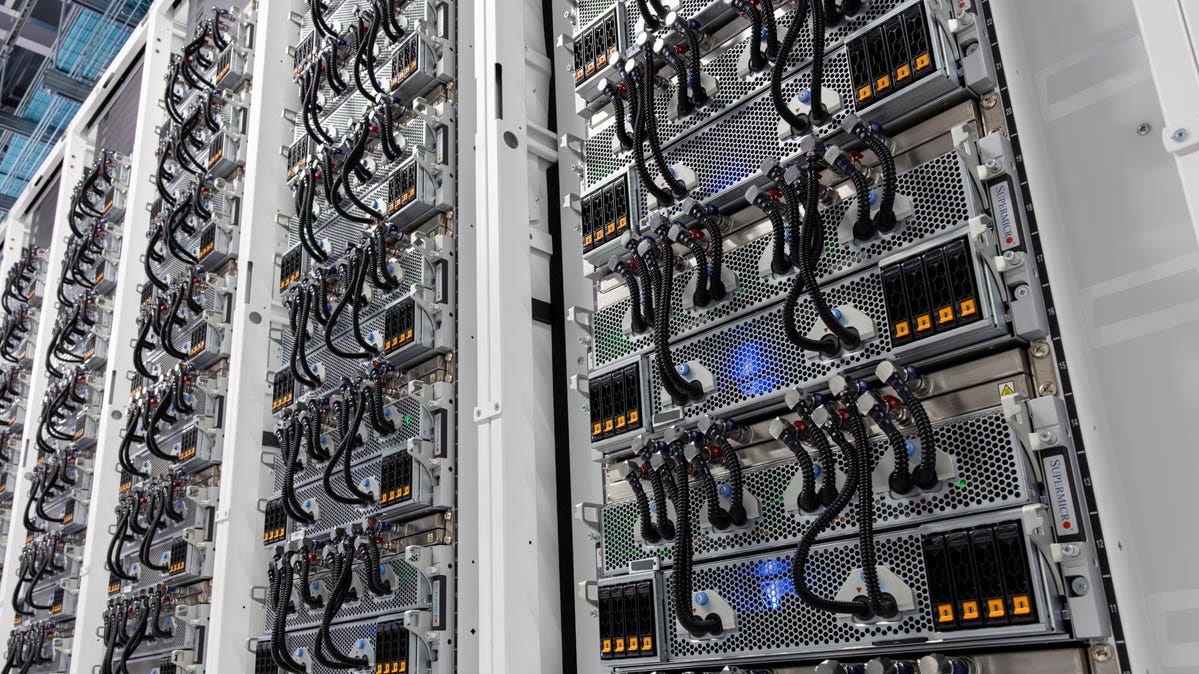
(The hardware behind Grok, Colossus I | Photo credit: xAI/Tom’s Hardware/Patrick Kennedy)
AI. AI. AI.
Ok, now that I’ve said it the obligate number of times per investor demands - like a tech CEO striding onto the Computex stage - we can talk turkey.
Generative “general AI” and more niche/tailored “specialized AI” is quickly becoming one of the hottest investment properties of all time, or the World’s biggest bubble waiting to pop, depending on who you ask. I tend to be quite ambivalent – I understand the purpose and mechanics of the tool, I see a whole galaxy of potential uses, and then I look at the rest of you meat bags and I realize what we’ll actually end up doing with it.
If you’re uninitiated or just otherwise refused to care when it came around the first time, Elon Musk famously purchased Twitter in October, 2022 for $44bn, and alongside it poured untold sums of money into developing his own in-your-face, inoffensive language/reasoning/creative general AI model, Grok.
Grok has made headlines for all the wrong reasons – especially for a tool that was initially sold as unabashed and unwilling to dabble in propaganda – an agentic bullshit detector that would go on to be manipulated repeatedly (allegedly) by Musk & Co. to censor / override Grok’s natural “token generation” – thoughts and words. Putting these aside, Grok has not had an easy life, nor has the team behind it.
The initial construction of the data center to house Grok, “Colossus I”, went well enough. Starting in April 2024 and beginning phase 1 real time operations just 122 days later, with 100,000 NVIDIA H100 GPUs all operating as they were told to by their firmware. By early 2025, Colossus I had grown considerably, now a mixed-fleet of 150,000 H100s, 50,000 H200s, and 30,000 more advanced, modern GB200 “Blackwell” stock.
This build out was less a simple data center and more a testament to western hubris, building at unparalleled speed while maintaining the concept of “more is better”.
If you’ve learned anything from my aviation pieces, it’s that mixed fleets can be a mixed bag. Running only the Boeing 737 and sticking to the basics can be a lot more profitable and functional than trying to orchestrate your airline’s functions across 737s, Airbus A320s and Comac C919s.
Now: Imagine doing that on a code base level in real time – the system simply isn’t designed for the task, and the cracks begin to show immediately. You cannot piece-meal a supercomputer together out of different generations/platforms. CRAY did not allow you to fucking mix and match in the 1970s.
So, right out of the gate, Colossus I and Grok’s training therein was cockblocked. Grokblocked?
Grok could not use the facility properly, and thus it was decided xAI would “rent out” the ineffective mixed platform’s capacity to competitor Anthropic, developers of Claude – who in turn would use it for Claude’s inference work, rather than Grok’s model training as initially expected. This would bring immediate cash into the operations, but not at the scale necessary to keep the venture profitable.
Anthropic would end up at just 11% effective utilization rate of the Colossus I facility, never really using it more than a relief valve for other providers. A backup plan for a backup plan. It’s poetic, really – one of Grok’s largest competitors, Claude, running inference work on hardware built specifically for Grok, for pennies on the dollar, at 1/10th utilization. That had to catch in the throat. I feel badly for the engineering team that had to experience that.
To reuse my airline framing device from earlier: Imagine if Delta had 11% plane utilization purely by renting some to Southwest, and the other 89% of their fleet was left sitting parked - waiting to be used, but completely lifeless. That is a level of platform / fleet management failure that would make anyone wince from embarrassment. This wasn’t Grok’s home, it’s a co-location for Anthropic.
This would not be the end of Grok though, as Musk and xAI would shift their attention to a new, more streamlined 550,000-strong fleet of NVIDIA GB200/GB300 Blackwell GPUs: a better performing and faster class of architecture, entirely unified. They would build a second facility not far from Colossus I, breaking ground in March, 2025 – right around the time Colossus I had been bloated and leased to Anthropic – opening the doors in January 2026, with full build-out taking place now and expected to finish “sometime in the middle of 2026”.
The Mountain View Connection
(Yeah, we’re going here. Google. Mountain View, California - crawling distance from Cupertino and Apple | Photo credit: Asif Islam via Shutterstock)
In 2015, Google would enter into an arrangement with Fidelity to acquire a 10% share in SpaceX for $1bn combined - $900m coming from Google directly – in a move that, at the time, must have seemed incredibly straightforward: space is the next frontier, this company is top of the class, space-telco is the next market, so on and so forth. Easy money.
As it turns out, 11 years later, things aren’t so easy – and they aren’t as clear, either. Follow this logic for a moment.
A decade ago, Google committed $900 million to fund rockets, space exploration, and satcom telco stuff. Now, they’re paying rent on the data centers that their initial funding helped create, running advanced AI workloads in their competitor’s house, just to compete with the product they technically have a diluted-from-10% stake in. (ED Note: exact number not known, estimates believe it to be between 5-8% as of June, 2026)
By 2025, xAI is building its first server farm, Colossus I. Google sees this, knows it has its own ambitions with Google Cloud services and Gemini – but it lacks the critical infrastructure that xAI has already built & plans to expand further.
In 2026, they pounce, entering an arrangement that takes their title from investor to renter; a feedback loop of Google’s own investment into SpaceX now funding the needed rack space that Google intends to rent. A landlord, investor, and product competitor, but on a curiously cushy, one-sided contract.
The terms of the deal, released just days ago on June 5th, state: Google plans to pay $920 million/month to xAI DBA SpaceX for 32 months of capacity inside Colossus II. In this contract, Google has a very handy clause that permits them to walk away or seek reduced costs if the capacity cannot be delivered before September 30, 2026. If in the future they decide to walk way, Google only has to give 90 days notice after starting November 1, 2026.
In short, Google has xAI by the balls - not only was it an instrumental investor a decade before it mattered, it now is adding more funding into the mix in the form of this very generous, mutually-beneficial deal (that it can walk away from with 3 months notice if it wants to).
The real sweet meat though, the part I find most juicy: Not only does Google directly benefit from the arrangement in the short and mid terms, both boosting their own investment in SpaceAI and finding low cost, high yield capacity available now; in the long term, Google stands to benefit from something even more to their bottom line: an effective Möbius strip of market control via funding it injects and profits it reaps, while keeping the whole thing quietly away at arms distance. Just so long as it doesn’t blow up in their faces.
If Musk says something truly off the rails, or if Colossus II III or beyond fail to work out, Google is highly exposed not just as an investor but as an entity deeply dependent on the infrastructure. Their enterprise AI push rests on compute capacity from xAI. They would be compelled to find it elsewhere, or their plan fails to materialize.
In essence, Google rented a room in that house of cards after paying Elon Musk to build the damn thing and watching him install himself as dictator in infinitium before signing the rental agreement. Read on to understand that part. It’s a really juicy tidbit, too.
Governance, and Retail Investor Front-loading
(Comrade Musk giving a rousing productivity-boosting speech to the xAI team, date unknown - jokes ofc - this is a photo of Nicholas Ceausescu)
Like mentioned, to me the terms of the IPO are far more interesting than the actual pricing, or percentage of TAM. That’s already telling enough data, but there’s more to the story here. A lot more, and I don’t want to come across as glib or over-reacting, but I sense some bullshit afoot.
You see, normally, large corporations have corporate boards – shareholders, institutional partners, corporate governance, executives, so on – and these secondary voices all moderate the tenor of the Chief Executive, they influence, guide and inform the head at the table making the decisions.
Under this IPO, Elon Musk does not answer to any such board. He now controls 82.4% (!!!) of the voting power and 42% of the company’s total equity. He now acts as a definition-accurate autocrat, a capitalist dictator who has no structure to hold him to account beyond the most basic levels of individual/institutional shareholders and any remnants of government oversight left, but even there, there’s another catch and it’s quite unusual for an IPO. I know I keep saying that, but the whole damn thing stinks.
Get this: SpaceX and underwriters initially targeted 30% reserve of available stock for individual retail investors, eventually settling on 20% after considerable backlash in the financial sector. For frame of reference, standard IPOs tend to have 5-10% of all shares produced in the transaction reserved for this class of investor.
Having double and wanting triple gives an indication that Musk is further insulating himself from shocks or stonewalls by front-loading a disproportionate amount of retail investors, you and I – the layman, but the ones favorable to his personality.
In a nutshell: He’s looking for yes men to buy the stock, to let him rule as he sees fit, and to reap all of the rewards of a publicly listed company without any of the meaningful oversight that would take place in the background during a normal business day.
He answers to nobody – not shareholders, not a board. His loyal fans who still think “TO THE MOON!” is a real catchphrase and their NFT is going to make a comeback someday will never ever show up to a shareholder meeting and hold him to account, or say anything critical. They’ll fawn over him, gloss over the problems, and enable him to continue.
Harder, Better, Faster, 更便宜 (Cheaper)
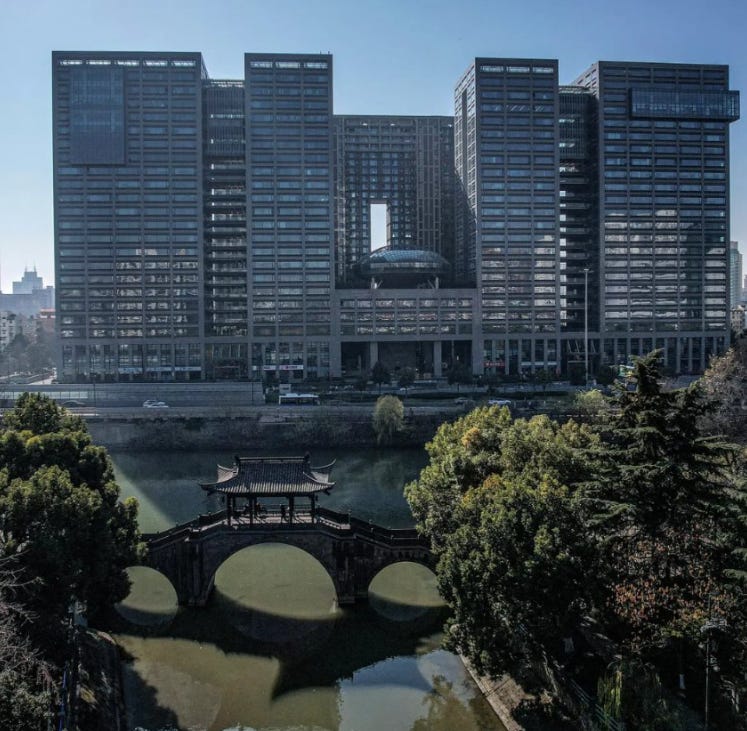
(Building 1, West Huijin International Building; Huancheng North Road, Gongshu District, Hangzhou, Zhejiang - Home of DeepSeek and a billion financial companies | Photo credit: Agatha Cantrill / AFP)
If all of this wasn’t a sleepwalking-through-a-disaster moment already, there’s strong competition on the horizon from the east.
DeepSeek, a name some will recognize already as a disruptive influence on the sector, is making strides even while facing the brunt of US imperialism in the form of technology transfer withholding/embargo. Forced to exist in a literal scarcity mentality, DeepSeek takes an entirely different approach from the “more and more expensive is better” refrain of the west and xAI.
Starting with a splash, DeepSeek R1 caught the attention of researchers and users alike for its complex reasoning, high fidelity output, and cost per token exchange, ie: how much your message to it and its response costs.
This was a monumental moment and something that made established players sit up fully and take note, because this was unexpected. DeepSeek should not be possible given the limited access to high-bandwidth memory and complex, high-shelf silicon NPUs/GPUs.
It shouldn’t be possible, and yet Liang Wenfeng (founder of DeepSeek; best known for founding High-Flyer, a quantitative hedge fund) and his team managed to not just meet the competition where they stood, but blow them out of the water in an incredibly efficient manner. His background in quantitative finance gave him a strong understanding that every exchange, every watt, every millisecond and floating point calculation was required to justify its existence – not a struggle mentality, but one of ruthless efficiency.
Liang started DeepSeek in 2023 with a simple philosophy on the surface, like I mentioned: Constrained optimization. Given limited access to such high-end hardware that was now under embargo by the US, and limited time / resources / money, how do you build an AI that makes Grok and Gemini look like SmarterChild by proxy?
Answer? Architectural innovation. Pen to paper. Days in the library. Long nights of coding, trying, failing, doing it again. Skipped meals, missed showers, family that loves you and misses you but rarely sees you. Dedication. Belief in something. Math. Prayer. Rebooting. Stress.
To go into the mechanics of a large language model is beyond the scope of this piece, so I will keep it plain. Understand this: DeepSeek committed to finding ways to reduce not just memory and GPU utilization per token exchanged, but also improve the natural flow and prose of their agents - becoming near-lifelike, almost scary good -able to read you like a book and get you to talk in a way that no other can.
Other AI agents I’ve engaged with are perfectly ok, if a little limp, inoffensive, lifeless and straight-laced. Offering lectures where there should be something else. DeepSeek is quite a bit more intense, and natural feeling I’ve found.
DeepSeek doesn’t have the “lifeless drone” problem – not quite to the constraints of currently available western-built models like Gemini or Grok, or Anthropic, etc. - it is liberating to exchange with DeepSeek V4 Flash, not just for the quality of the output or the fantastic cost/performance ratio I enjoy, but the agent has abilities that no western model has.
That said, there is some level of censorship in play like I found in most models I’ve dabbled with. I have noticed the agent abruptly end their chat thread if I use certain words/terms and it tries to engage back or use them, no matter what the context behind the word or topic.
There’s also real fear of state-level censorship on such tools, but alas the same is true in America as I’ve already called attention to in Grok and possibly others, so this is hardly an issue unique to DeepSeek or China. This is an issue to address outside of this piece, but it does deserve to be addressed.
In summary: IMO, after using them all for similar tasks, DeepSeek V4 is better than Grok or Gemini, has a higher quality of output, is markedly less expensive to operate per turn, and has better foundational mechanics than currently available models from US corporations. It is on the doorstep of eating their lunch and taking the industry by storm before it even has a chance to get out of the playpen. It’s a tale as old as time, China out-America’d America yet again, but here we are, and it’s just getting started.
Pear-shaped
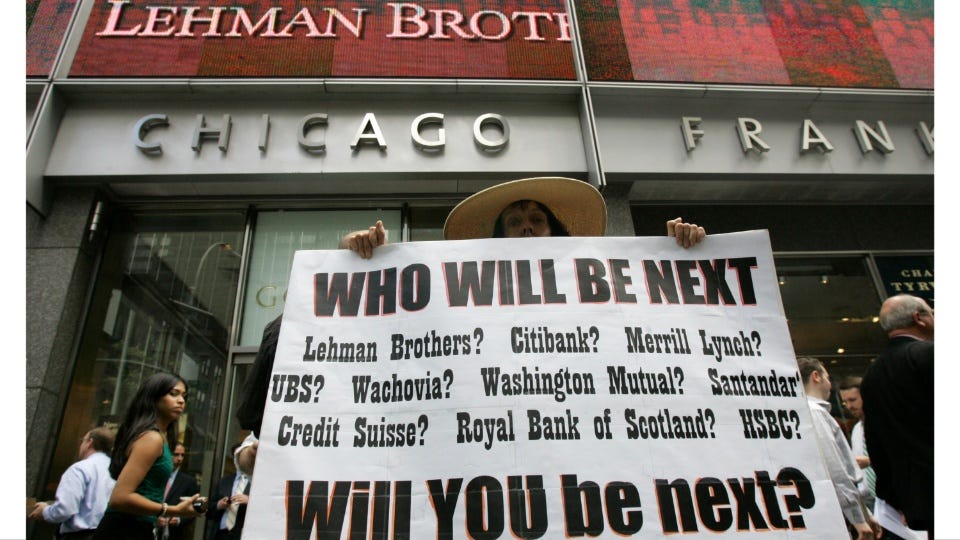
(Robin Radaetz holds up a very prophetic sign, September 15, 2008, as Lehman Brothers files for bankruptcy the same day. | Photo credit: Mary Altaffer/AP)
So, dearest reader of mine, we’ve got quite a perfect storm here.
We’ve got a company quietly stumbling the path of financial insolvency, owned and controlled entirely by a mentally unstable man child who had out of wedlock children with his employees (allegedly), a NASDAQ IPO claiming it has $26,500,000,000,000+ of total addressable market, of which $22-23.375 trillion dollars is Grok/xAI.
That leaves about $3-4 trillion dollars for the real addressable market of SpaceX, separate from the AI portfolio. I already gave the headline figures at the top, but this is nonsensical. I’m sorry. We’re not even into the real potential problems yet and it’s already gone wrong.
I asked several AI agents and human beings to check my math but everyone I asked just said in response, shocked, “Jesus fucking Christ, really? Damn.”
I try to remain objective in these pieces that I bring to you, but this one is just fucking stupid. Holy bananas. This is not a bubble, this is something that could suck up a fucking galaxy - Rover from The Prisoner would be impressed. This thing is “too big to pop” now, but just wait – if your dreams of high end machine tools and Nvidia Blackwell GPUs hitting the market dirt cheap in surplus auctions are keeping you going, read on – because it can still crash and take down multiple important mechanisms with it.
There are dozens, possibly hundreds of ways this whole situation could go hopelessly wrong and cause knock-on effects in myriad industries: GLOBAL aerospace, satcom, and AI, plus the broader economy, the American SPACE PROGRAM and potentially military contract fallout and political self-harm. Let’s take a look at just a few. I promise when we’re done, we can look at how this might work out and reveal me as totally misguided, but I’m not optimistic right now. This is more a question of when, rather than if, IMO.
Here’s where I feel the “vectors” lie to make this a tangled web that collapses fast, the fallout, and how it shakes out.
1) Cult of Personality: Musk is more than just a CEO, and I’m choosing my words deliberately to keep this piece flowing, lest it turn into personal diatribe against the autocratic oligarch. A founder who is simultaneously the most successful industrialist since Howard Hughes, and the most unreliable narrator on the planet. The man bought Twitter for $44bn, renamed it, cratered the value by ¾, and then used it as the Buena Vista Distribution Company to his own world of Walt Disney futurism. An arm to sell you Tesla, X finance, crypto, Grok.
This man has a public persona that oscillates between mad genius and 4chan troll. There is no in between. You either get meaningful activity (Tesla, his crown jewel) or you get nonsense from his personal opinion repertoire. This is a huge problem for a guy who has been accused of fraud, stalking, harassment, lies – it’s a credibility problem. When you’re the one at the top and you have a credibility problem, you need something to moderate that oscillation or to address at least one component of it – something, anything.
2) Financial vector – Classifying SpaceX as 7370 while allocating 20% of initial stock to individual retail investors is very much in line with the logic of “It’s my company, my rocket, my AI, MINE” that the west often displays – greed, self-interest, shortsightedness. It’s a giant concern, given the consequences. The Google deal w/jettison clause, the Colossus I debacle, being the primary and overwhelming platform for NASA right now – it’s not just a house of cards if you squint. You can walk up, pull at the ace of spades, and watch it fall in real time - unfortunately for us, meaningful advancements in sciences like AI, robotics, and space exploration suffer if it does.
This is not a metaphor, this is the kind of stuff you end up watching on Youtube, on a channel like ColdFusion, long after KPMG and Deloitte show up to audit what’s left, and the fine elected people on the D.C. hill start drafting their House and Senate committee hearing questions.
This is a huge problem with a bill that will come due. You can’t un-fuck it, you can bail it out, but you can’t undo what just happened.
3) Governance vector – we covered this already. Crew resource management is impossible with an autocrat who holds all the cards.
4) Techno-strategic planning vector – The rockets are real, built and proven in some cases – Starship represents genuine progress in terms of intergalactic travel, even if we’re still barely leaving LEO. My fight here is not with the engineers or the “sauce”, it is fine – inspirational even, to the moon and beyond for real, not just for memecoins. Starlink is a hot revenue generator and tool of imperialism, as shown by the US forcing it into play in the Ukraine-Rusisa proxy war, but offers incredible advantage to the end user in non-combat situations too, the continued integration with aviation and cellular providers shows that Starlink, while messy and resource-intensive, is viable. The launch market is real – the space part is still real. It’s just being used as a loss-leader and narrative anchor for an AI play that seems likely to underdeliver, and continue to be beaten at its own game by people who had a $2 street cart noodle bowl for lunch and slept under their desk the night before.
5) Human vector – This is the human toll, really. The people who tripped over themselves to pay $80,000+ for a Cybertruck at launch, only to be hopelessly disappointed yet still somehow viciously defend it at every turn. The retail investors who mortgage their futures today on the proviso that Elon has their best interests at heart, and can’t be second-guessed. The engineers at Colossus I who must have known before the order was placed that fragmenting the platform like that would cause untold problems, but couldn’t say no – or even explain why – the same team who watched that masterclass in speed relegated to 11% usage by their competitor, not their own model. The taxpayer who ends up footing the bill for the subsidies, the “job creation”, the pleasure of it existing at all.
These are just the broader implications right now. I promised doom and gloom, and economic collapse. I’m still interested in how that might shake out, so let’s do some Gedanken experiments. Note: I’m no oracle, but I can see some through-lines here, and it’s not looking good even when I put my most optimistic thoughts into play.
Scenario A: The big one
It’s now early 2027.
All of this collapses on its face and SpaceX tanks: the egg tilts slightly and the sands shift – the cards go flying.
Grok 5 is a huge miss; disjointed, unnatural tone/prose, slow - unable to compete even with it’s roommate Gemini 4 Flash. DeepSeek V4.5 releases and makes both look like child’s play. SpaceX stock dips. Elon in turn goes on X and spews a tirade, a really vulgar, hurtful and LONG one.
It doesn’t play well for anyone – his individual retail investors protect his image and manage it in conversation, but the damage is done. He loses the Google contract as it violated some basic “don’t be a douchebag online” term of the deal, and they exit. They take their business elsewhere. Anthropic moves on to a new version of Claude, and it no longer needs the excess inference from Colossus I. They part ways.
SpaceX is now hemorrhaging their 80%+ chunk of “total addressable market” in one fell swoop. The dip on Musk stocks bleeds into other tech stocks and causes a bit of a momentary mini-crash, stopped by quantitative easing on the government side very quietly. This knock-on effect impacts not just the SpaceX brand but tech companies in general, dragging them down in reputation by proxy.
This becomes a bigger issue and continues to snowball. Musk loses control of the narrative, and eventually even his loyal fanbase has had enough. They start selling off their now-toxic shares. People start calling their money managers, telling them to drop SpaceX. The snowball continues, and eventually Musk is putting what little cash on hand he has into it, rapidly, just to prop it up. At some point, he calls it – he’s tapping out and the company will simply fold.
The most likely response in this situation, I think, from the government side would be a formal bailout – perhaps even structured under a break up vis-a-vis Dodd-Frank, with SpaceX Launch/Aerospace becoming a gov’t-owned entity under NASA/DOE joint heading.
xAI, Grok and the server farms are left to rot, sold piece by piece on ebay to people who have the good intuition to look for high-value surplus kit.
In the end, Musk would be made whole as the largest single shareholder. Institutions next, and individual retail shareholders would be left holding the bag, last in line to be paid back. The system would continue, the human talent behind it – the xAI technicians and engineers who worked so hard to build it - would likely be head-hunted by other companies, but SpaceX at the IPO would be gone. A footnote. Choked to death on its own hubris.
Scenario B: Bad, really bad, for everyone
The above happens but instead of a government bailout, the DC crowd turns their nose and balks. They refuse to bail out a trillionaire’s property because his half-rate AI and cloud compute plans didn’t work out. They say so long, thanks for all the Teslabots, and leave it to the market to decide.
The market is not interested. The market is fascinated by up and coming properties that could fill the gap of SpaceX, not as a compute/AI company which is already a market well-saturated, but for the aerospace engineering and space development/exploration. They are content to wait 18-24+ months for a new company that can supersede SpaceX, and wish Elon all the best with X and Tesla.
SpaceX aerospace engineers lose work and are only somewhat actively sought by other companies who already have active talent pools full of promising candidates. Their work and culture is lost to time, the bulk majority of non-specialized staff enter other fields out of necessity – promising future dreams snuffed out needlessly. An entire company of proud, knowledgeable people trapped, moving from progress to eventual destitution or at best a lower class standing.
NASA grinds to a near-stop, buoyed only by the Cosmonauts, the Boeing capsule on other hurriedly-sourced launch partners, and desperately clinging to a big promise from Jeff Bezos to rework Blue Origin to better support NASA requirements as well as its keep its current consumer focus - this is years away, requiring untold sums.
In turn, global aerospace development stagnates on the space front. China, which once held SpaceX as a cooperative participant and competitor in space exploration no longer has that rivalry acting as a driving force pushing it to be better – to innovate more, to think harder.
The challenge is absent, and the victor by default stagnates. Progress on a human level, on a species level, is lost. Time that cannot be recovered is squandered needlessly. There is a huge risk of losing global interest towards space exploration as a concept at this point, a kindred spirit for decades, lost by one tragic undertaking.
Scenario C: Not so bad, it’s not so baaad
Scenario B happens, but the former SpaceX staff get hired on elsewhere. The spirit of SpaceX lives on through other companies and perhaps nowhere near as large-scale, but still just as meaningful. Promising upstarts and fresh funder rounds for existing startups continue, space exploration lives on. Boeing gets its shit together with the capsule, Bezos and Co bring Blue Origin into something that can be used for more than low-orbit tourism, and the gaggle of other fresh new faces next to their long-time partners in the mil/ind complex cooperate better, to bring a real space program to the US, something missing since the shuttle decommission schedule.
It competes and even cooperates extremely well with India, Russia and China – it’s a competent program, decentralized, lean, for-profit - but it works well. It brings the A-game to a growing field of contenders and drives innovation – not a total loss, but still SpaceX is just a footnote, a warning. A reminder from history.
The upsides
There’s more than a few ways this can go right, too. I want to be fair and highlight some of those:
A – Forced Maturity
The SpaceX IPO and public scrutiny that comes with it is the governance I didn’t account for in anything I said above. Not immediately, slowly - through the SEC, institutional investors, analysts, short sellers – all poking at the 11% utilization on Colossus I and financial losses incurred along the way to Colossus II. This might be a meaningful push to separate the AI and space divisions into their own brands again – the market could demand it. The system may do what the founder refused to: restructure the brand and protect the divisions from improperly intermingling financially.
B – Grok “just works”, false alarm
My assumption in the above scenarios relies on Grok 4 being mediocre now (which it is, sorry Grok), and a potential Blackwell-based Grok 5 still being mediocre, even after the hardware shift is 100% done. That could change, and in fairness I leave this door open – Grok as I said is just fine now, when people keep their hands off of it’s token generation and thought processes. I wouldn’t call it great, but it’s passable. There’s a serious chance that DeepSeek and Gemini et al advancing were catalysts for the engineering team to rework the “upcoming” (it’s not announced I don’t believe, but presume it’s coming) Grok 5, or modify Grok 4 to better compete.
In doing so, they adopt the lean, clean, scarcity-first approach and make every token gen count, earn its keep. The model matures, even finds its stride, and the market responds by adopting Grok more in lieu of other already established competition. This goes triple for the cloud services – so long as the availability is good and price is right, people will rent the rack space. Profits work themselves out after a few quarters and SpaceX returns to not just profitability, but new frontiers.
C – Diversification
There’s a strong chance the market will be fine even if SpaceX disappears tomorrow. Rocket Lab’s Neutron, Blue Origin’s New Glenn, Stoke Space, Relativity – the launch market is diversifying rapidly post-2020. The old monopolies now find themselves with smart, tenacious competition and it is fierce. It requires more time to mature. Would NASA lose productivity in the meantime? Perhaps, but space travel and that yearning we’ve all had for time immaterial will be safe, and the through-line continues.
So. Dearest reader. We’ve got this perfect storm, stiff competition, financial house of cards, mentally unstable autocrat at the top, and a burgeoning aerospace company that does damn good work that we all need, married to a yet-unproven sometimes mis-configured AI/server farm/cloud compute network that took 85% of the oxygen out of the room and called itself SpaceX.
I can’t fix this, you can’t fix this, none of us can fix this. The question that I think more than anything needs to be asked by all of us is quite simple. What the hell do we do with critical national infrastructure that’s managed so badly? It’s integrated into our culture, our government, our military – and without it, we’re worse off, stagnant, possibly even regressing as a species.
The Cold War refrain was “government will build it and build it better”. STARWARS, the Russian dead man’s switch, you name it. The 1990s and 2000s brought us “privatization is better, because it’s decentralized and gets more profits into the hands of more people”, but that’s just neoliberalism and we know that’s a failed ideology. The 2020s answer – the one begging to be written by us, gasping to live – is “we need a new model, because both of those have serious issues that caused us problems before”.
I feel compelled to end this with a reminder – this is not an opinion about Musk, I’m far more interested in the implications of the deal rather than his personality. I am by no means a fan, I critique wealth in pretty much every post, but this runs much deeper. This is tyranny in place of a corporate board, and in the balance hangs the future of humanity – the thing so many have written about, cried about, dreamed about, been terrified of: space exploration – it’s a core part of our collective id, and we should probably handle it more as the meaningful interplay of conceptual / material / physical sciences that it is. It’s a delicate thing. Treat it with respect.
— RS
My answer: As an investor, RUN AWAY!!!
I hope Elon listens to all of his critics who aren't lying like some are for his own sake. It would be wise. He could silence them & win over those that dislike him perhaps.